 Alveena Ahmad
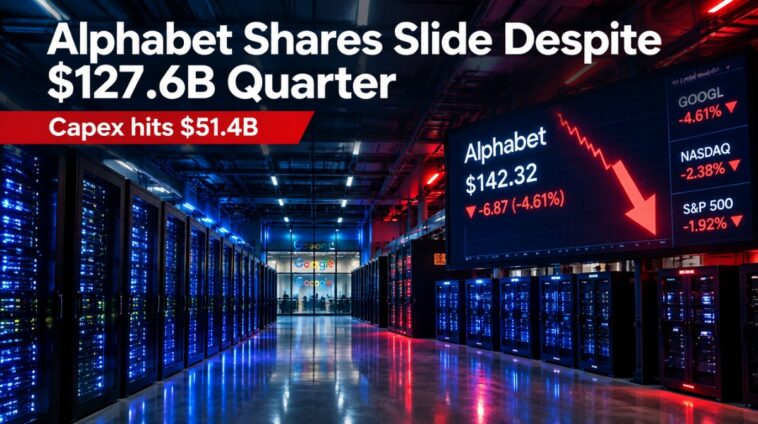
Alphabet reported third-quarter 2026 revenue of $127.6 billion, up 25% from a year earlier, but diluted earnings per share fell to $2.12 from $2.87 and the stock dropped more than 8% in after-hours trading on October 29. The sharpest pressure points were an $8.7 billion loss on equity investments and capital spending that more than doubled to $51.4 billion in a single quarter.
The company’s own Q3 2026 earnings release gives the baseline. Operating income rose about 30% to $40.6 billion, yet net income fell to $26.5 billion from $35.0 billion, which the release attributes mainly to that $8.7 billion loss on equity securities.
Cloud doubled, Search slowed
Google Cloud was the standout. Revenue rose 103% to $30.7 billion from $15.2 billion, and the release says sales of TPU systems contributed meaningfully. Google Search and other revenue, the business that pays for most of the company, grew 12% to $63.4 billion from $56.6 billion. A summary of the day’s AI news from The Neuron notes that search advertising growth has slowed from 19% in the first quarter to 12% in the third.
CEO Sundar Pichai said AI investments are driving overall Search query growth, including commercial queries, and that Google’s first-party model APIs now process nearly 32 billion tokens per minute, more than four times the prior year.
Where the money is going
Capital expenditure was $51.4 billion, up from $24.0 billion a year earlier, and trailing twelve-month capex now stands at $159.8 billion according to the release. Market analysis from XTB adds that free cash flow was negative $9.1 billion for the quarter, and that the company raised roughly $28.7 billion through bonds and $12.4 billion through equity issuance. XTB also reports that the earnings miss was large, with consensus EPS near $3.00 against the reported $2.12, though it does not name the analysts behind that estimate.
Full-year 2026 capex guidance from July was $195 to $205 billion. XTB calculates that hitting it implies roughly $63 to $73 billion in the fourth quarter alone.
What freelancers and small agencies should take from it
For anyone selling SEO, content or paid search services, the useful number is not the stock move. It is the 12% Search growth next to the news that Google is expanding ads inside AI Search to more international markets, with new multi-turn ad formats planned for the United States, per The Neuron’s summary. Ad inventory is shifting toward AI answer surfaces, and clients will ask what that does to their budgets.
That fits a trend beingguru has tracked, from what clients are paying for in generative engine optimization to the funding flowing into AI search optimisation tools. Gulf and Pakistani freelancers who can explain visibility inside AI answers, not just classic rankings, have a pitch that matches where Google itself is putting its money.
There is also a cost signal. Google is spending at a pace that outruns its operating cash flow, and it is selling TPU capacity to outside customers to help recover it. Cloud and AI tooling prices that freelancers depend on are set by companies under exactly this kind of pressure, so expect pricing and usage limits to keep moving.
The fourth-quarter test
Investors will watch two things next: whether Search growth stabilises above 12% as AI ad formats roll out, and whether a fourth-quarter capex bill north of $60 billion is matched by more Cloud revenue like this quarter’s. Alphabet has not given a firm 2027 figure in the release, and secondary reports of spending above $300 billion should be treated as unconfirmed until the company states it.