 Hajra Naz
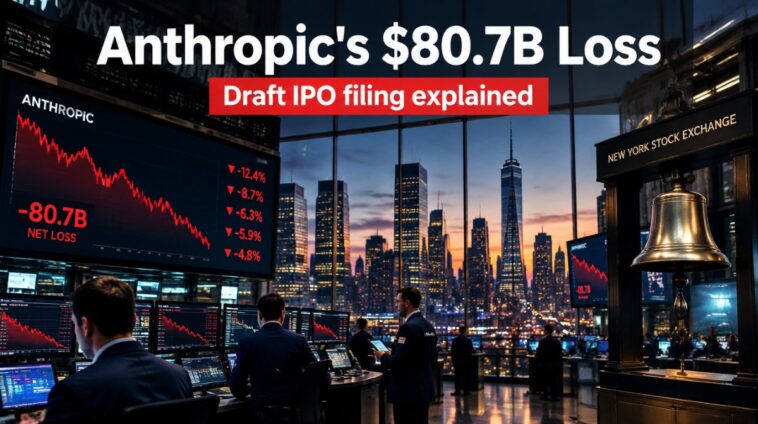
Anthropic recorded a net loss of $80.7 billion in the first half of 2026, according to a draft IPO prospectus reviewed by The Wall Street Journal. Revenue for the same six months was $16.3 billion, up from $1.1 billion a year earlier, and about $72 billion of the loss came from non-cash accounting charges.
The figures were reported on October 20 and summarized by TechStartups, which points to the original Wall Street Journal report. The filing is a draft, so numbers can still change before any public offering. A potential November listing is reportedly being prepared.
Reading the $80.7 billion loss
The headline number looks alarming, but the breakdown matters. According to the report, nearly 90 percent of the loss, roughly $72 billion, came from accounting charges tied to changes in the value of convertible notes and other financial instruments. That is a paper charge, not cash that left the company. Anthropic’s loss in the first half of 2025 was $13 billion by comparison.
The cash side of the story is the infrastructure bill. Anthropic spent nearly $9 billion on computing infrastructure in the half, more than it spent in all of 2025. The prospectus also reportedly shows computing commitments that could reach $750 billion once agreements still under negotiation are included.
Where the revenue comes from
Revenue of $16.3 billion is almost 15 times the figure from a year earlier. The same reporting says roughly one fifth of first-half revenue came from just two customers. That concentration is a risk factor any IPO prospectus will have to spell out, because losing a single large buyer would move the numbers noticeably.
Reuters, cited by TechStartups, reported that third-quarter revenue reached $16.8 billion, up 45 percent from the previous quarter, based on an investor at a pre-IPO meeting. That is a secondhand figure, so treat it as indicative until the prospectus is public. The same coverage says the offering could value the company at up to $2 trillion, which is also unconfirmed.
What it means if you build on Claude
Freelancers, agencies and small teams in Pakistan and the Gulf increasingly build client work on top of a handful of AI model providers. A filing like this tells you two things. First, the providers are spending at a scale that only makes sense if demand keeps compounding. Second, pricing and terms are still being set by companies that are not yet profitable on a cash basis, so they can change.
The practical response is modest. Keep client deliverables portable across at least two model providers, avoid hard-coding one vendor’s features into a product you sell for years, and track your own cost per task so a price change does not surprise you. None of this predicts a price increase. It is simply cheap insurance against dependence on one supplier.
What to watch before November
The public version of the prospectus is the document to wait for. It should confirm or correct the loss figure, show how much of the commitment total is binding, and name the risks Anthropic itself considers material. Anthropic had not responded to a request for comment on the loss at the time of the Reuters coverage cited above, so the company’s own explanation is still to come.